Posts

Real Vision's Stanley Druckenmiller interview (2018)

Image
Thanks to Liberty for pointing me to this excellent interview with hedge fund superinvestor Stanley Druckenmiller, conducted by Real Vision. Druckenmiller is a macro investor so anyone who is macro- oriented should definitely check it out. As he makes clear in the interview, he made most of his money in interest rates and currencies and doesn't do much equity investing, so small investors like me who are focused on stocks won't find much practical insights. Nevertheless, you can glean some thoughts about global macro issues. Of note, the interview covers loose money policy over the last decade and potential trade war with China. In my opinion, these two are the most important issues, not just in the immediate future but also over the next 25 years. Druckenmiller also gives the most important investing lesson he learned: one should always know whether they are on a hot streak (doing well) or if they are on a cold streak (bad). You should realize what streak you are on and a...
Purchase: WesternOne (TSX: WEQ)

WesternOne (TSX: WEQ) is being liquidated and it seems like an attractive investment so I took a position in it. I came across the idea from Sculpin at Corner of Berkshire and Fairfax (thanks). You can read the official press release but basically they are winding up operations and expect to pay out $2.20 to $2.43. It will be adjusted up or down by working capital but hopefully no negative surprises emerge. Initial distribution in Q1 2019 with another one upon liquidation. A shareholder vote is required but about 38% is held by insiders who approve the deal. So I think risk is low. The return is going to be driven by how much is paid out early. I'm hoping most of it will be paid out by end of Q1 2019. Purchase price (TSX: WEQ): $2.10 Return Expectation Liquidation price (conservative, low): $2.20 Return: 4.8%

Purchase: Nevsun (NSU)

I took a position in Nevsun (TSX: NSU) which is being bought out by Zijin Mining, which is one of the largest gold mining companies in the world. zijin is a chinese company that trades in Hong kong and there should be no risk with financing and the like. I owned Nevsun about 10 years ago and this buyout would bring closure to one of my earliest stocks. Since the spread is so small, this deal is not worth it for you if your holdings are in a different currency and you don't hedge; or have a US$-denominated account. C$ currency fluctuations can wipe out any gains. NSU also trades in USA but company is Canadian and all my dealings are in C$ and on TSX. Purchase price (TSX: NSU): $5.72 Return Expectation Takeover price: $6 Purchase price: $5.72 Probability of success (my estimate): 99% Return on success: 5% Probability of failure (my estimate): 1% Return on failure (my estimate): -56% (assume it drops to $2.50, the multi-year low from early 2018 (it has traded...

Sold: Monsanto (merger completed)

Have been busy, and probably not efficient with my free time, so haven't blogged much... Need to get into a rythm and dedicate more time to investing. I think I'm going to give myself to post once a week and maybe just do a roundup of things I did that week, articles I read,etc. Anyway, the Monsanto buyout by Bayer successfully closed a month ago and I just got around to reviewing it. As with most mergers, it took a bit longer than initially forecast--this is why if you are into risk arbitrage, you should always factor in a longer closeout process which lowers your annualized return. As I remarked a while ago, m&a is getting riskier with potential USA trade war with China, and likely followed by escalating trade war with Europe, so deal breaks are likely to become more common. Already several Chinese and high technology deals ran into issues. Overall return wasn't that spectacular but I was satisfied with it. Dividends added about 1.8% which is always a positive wit...

A Look at Tripadvisor (TRIP) and its Two Problems

Image
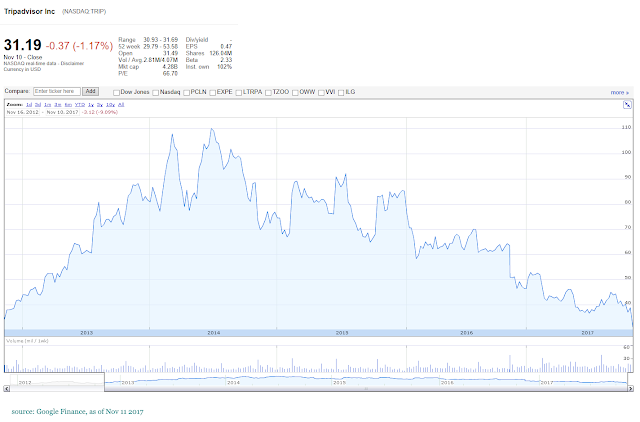
It's hard to find anything that seems cheap in the current bull market but as in any market, some stocks do sell off for various reasons. One of the ones that attracts me is Tripadvisor (TRIP*). As the chart below illustrates, the stock is trading near a 5-year low and is down about 70% from its 2014 peak (share count hasn't changed much and no major return of capital to shareholders). (* You can also own TripAdvisor indirectly through John Malone's holding company, Liberty TripAdvisor, with ticker symbols LTRPA/LTRPB. You should evaluate this option as well. Sometimes holding companies, especially if it is well run like most Malone companies have historically been, are better; sometimes they are not (there may be additional overhead/fees for the holding company, may have worse shareholder rights (doesn't favour minority shareholders) and market generally places a holding company discount on such shares and they may be illiquid)) I remember looking briefly at Tr...

First Look: Chipotle Mexican Grill (CMG)

Image
This isn't my type of company. It isn't in my circle of competence...but I've been researching and studying the industry. It doesn't have the valuation I like... but that depends on what one thinks is normal earnings. What it is, is a contrarian, broken, growth stock with very good backward-looking numbers and uncertain future. Overview Chipotle Mexican Grill (CMG) is a restaurant chain that apparently pioneered and popularized "fast casual" dining--basically a cross between fast-food (e.g. McDonald's, KFC) and casual (eg. TGI Friday's, Chili's, Boston Pizza). The food is Mexican, prepared similar to fast-food restaurants and priced in between fast-food and casual (a burger at a fast-food place might be $4 whereas a burrito at Chipotle will be something like $6). I don't know much about restaurants and am not really into food--sometimes I wonder if I should even be looking at this company--but from reading numerous articles, it se...

Sold: Cabela's (CAB) Merger Successfully Closed

I haven't had much time to blog and the highly-valued markets are frustrating for any contrarian or anyone waiting for low valuations. I have continued to research some companies and hope to write something up soon but the valuations are not compelling. If anyone has some stock ideas I should investigate, leave a message below or email me (If I am interested in them, I'll research it and write it up). In any case, the Cabela's (CAB) merger went through. This was a low return, short time-frame, situation and it worked out as expected although it went through a turbulent period. The stock sold off quite a bit after I bought it, possibly due to risk of the financial division sale not going through. That would have been the best time to enter this risk arbitrage position. It kind of seemed like this deal might not close and I would take a loss but fortunately it didn't turn out that way. As is usually the case with risk arbitrage, in hindsight the market always looks like...